Skip to research

Finding structure in noise.

ECE student at NIE Mysuru. I model transistors, markets and road networks as stochastic processes.

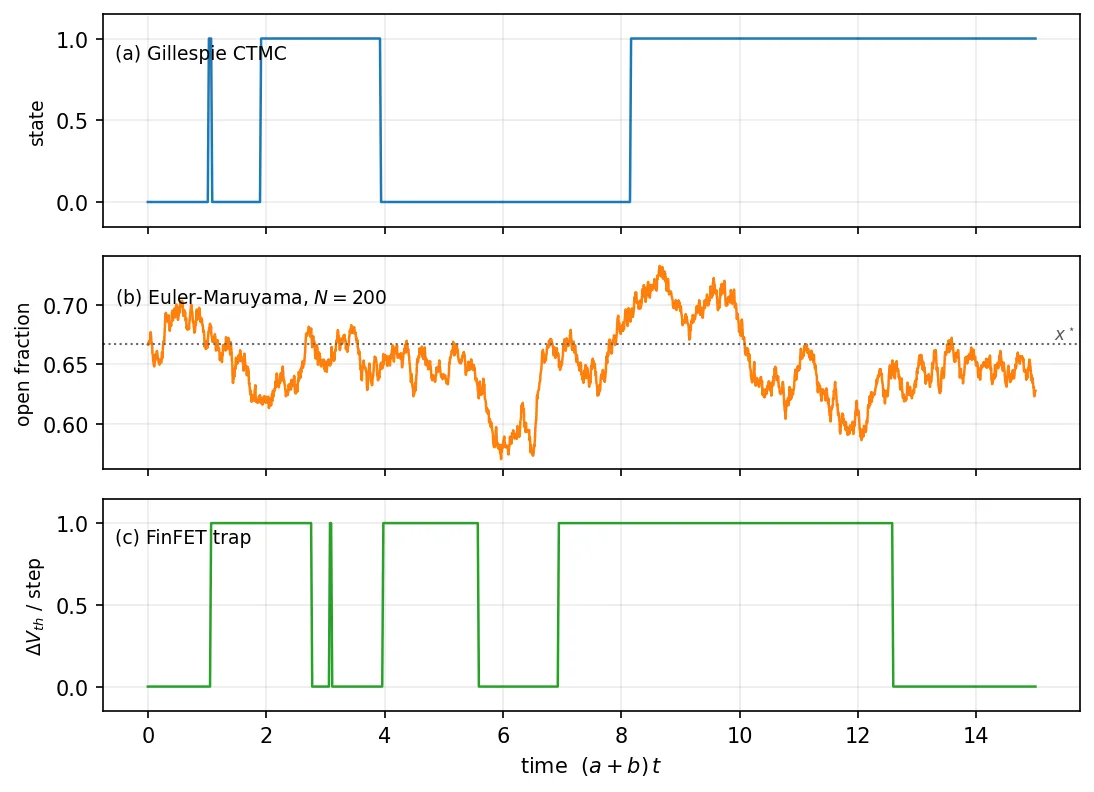
Three stacked time series: a Gillespie simulation of a two-state Markov chain, an Euler-Maruyama open-fraction path, and FinFET threshold-voltage steps from a single trap.
Simulated single-trap dynamics from my FinFET random-telegraph-noise paper.

Research

Detecting Hidden Trap States from Adjacent Dwell Times in FinFET Random-Telegraph Noise

Preprint, Zenodo, 2026. Presented at SRS'26, IIT Indore.

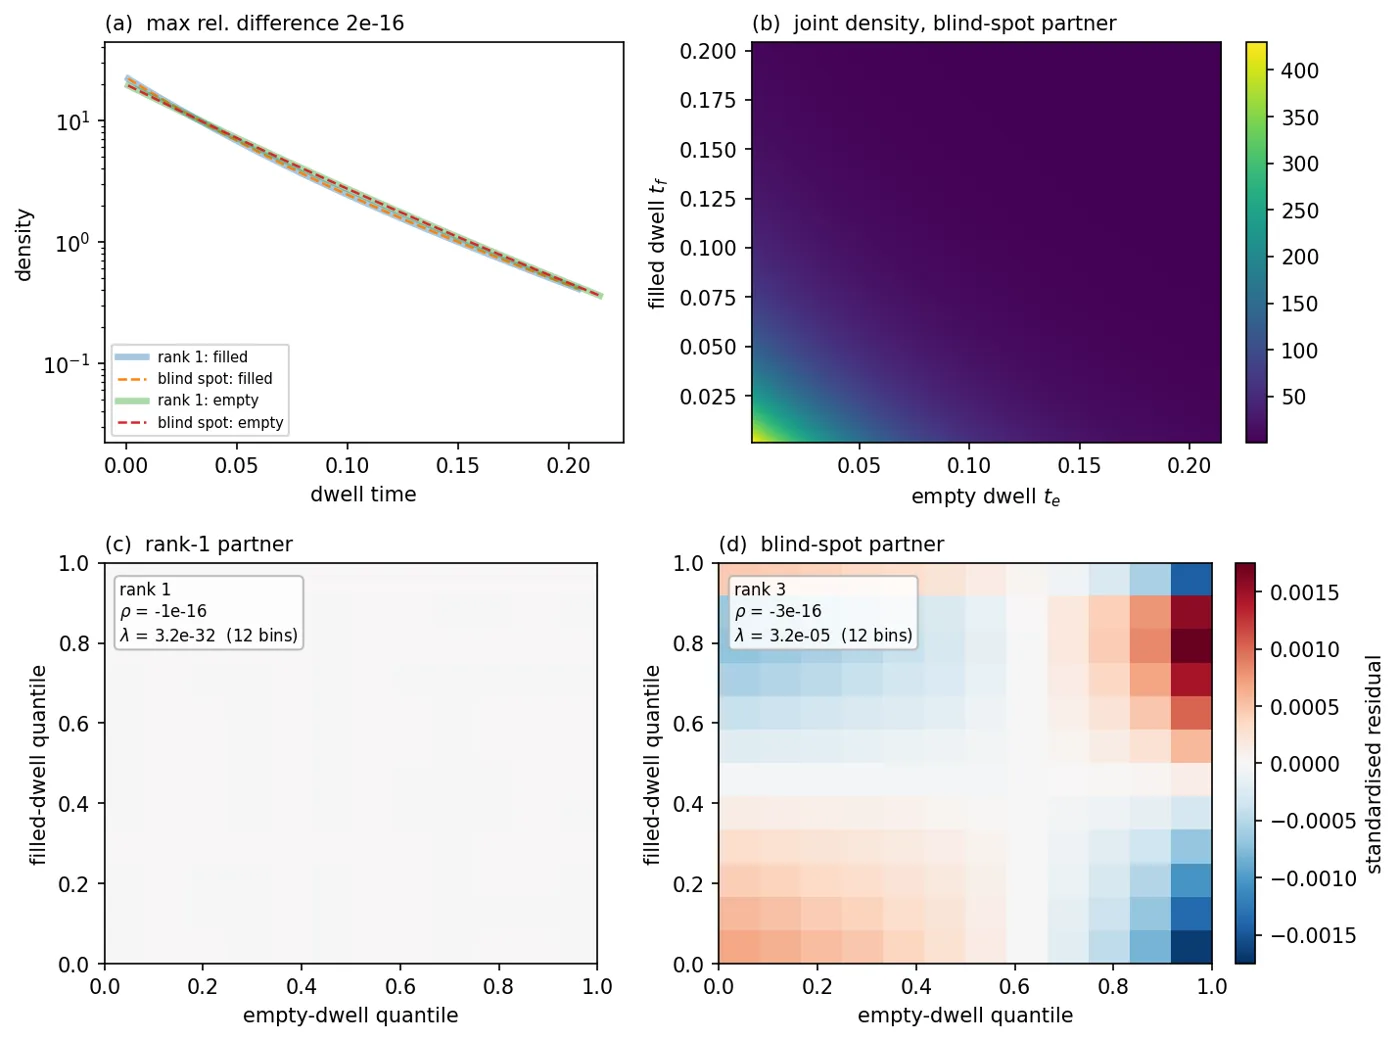
A single defect makes a FinFET's current jump between two levels, but the trap's internal states stay hidden. I look at dwell times in pairs: how long the trap stays filled, then empty.

With two hidden states per level, the correlation between consecutive dwells tells traps apart. With three or more, it can be exactly zero while the structure is still there. A test on the full joint distribution does detect it, given enough data.

  • Continuous-time Markov chains
  • Gillespie simulation
  • Chi-squared testing
  • BSIM-CMG + ngspice
Four-panel figure comparing dwell-time densities and joint dwell distributions for a rank-1 trap and a blind-spot partner with near-zero correlation.
Two traps with matching marginals and near-zero correlation, separated by their joint dwell structure.
8.1%

of 10,000 simulated runs were NPV-positive in the US and Europe baseline.

Monte Carlo economics of a $500M semiconductor fab

Preprint, SSRN, 2026.

A standard DCF gives one number for a fab investment. I simulate the uncertainty instead: construction delays, cost escalation and joint cost-yield shocks across three regions.

The NPV distribution stays left-skewed in every region. The India and Southeast Asia case had more upside, with 12.5% of runs positive, and a worse downside.

  • PERT delays
  • Geometric Brownian motion
  • Clayton copula
  • DCF

Projects

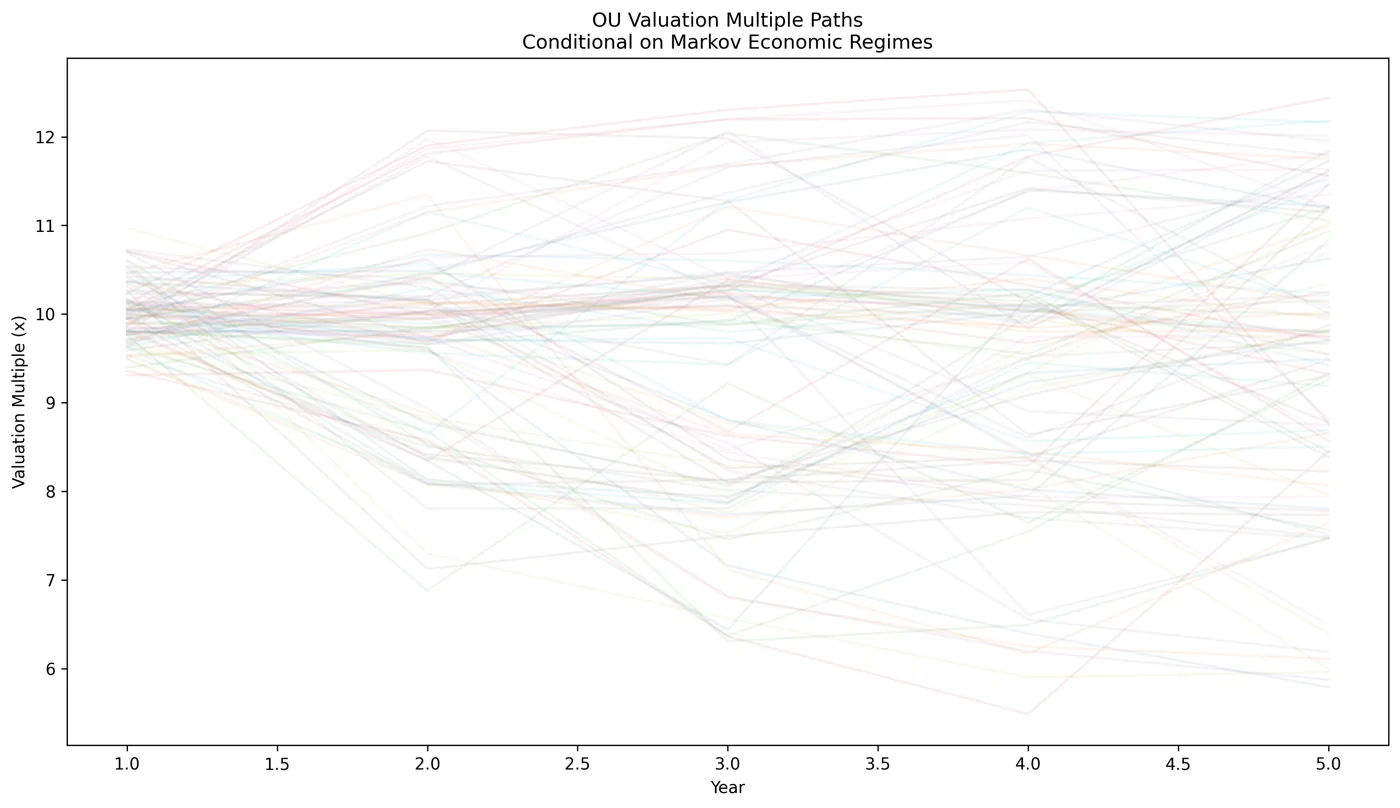
Fan of Ornstein-Uhlenbeck valuation multiple paths over five years, conditional on Markov economic regimes.

Stochastic LBO model

Markov economic regimes drive an Ornstein-Uhlenbeck exit multiple through a full buyout. Across 100,000 runs the median MOIC was 2.02x, with an 18.74% chance of losing money.

Python, NumPyRepo
121 x 121

MarkovLOB

A limit order book modelled as a Markov chain on bid and ask queue depth. It learns a 121 x 121 transition matrix from synthetic order flow, then generates new market paths.

Python, NumPyRepo
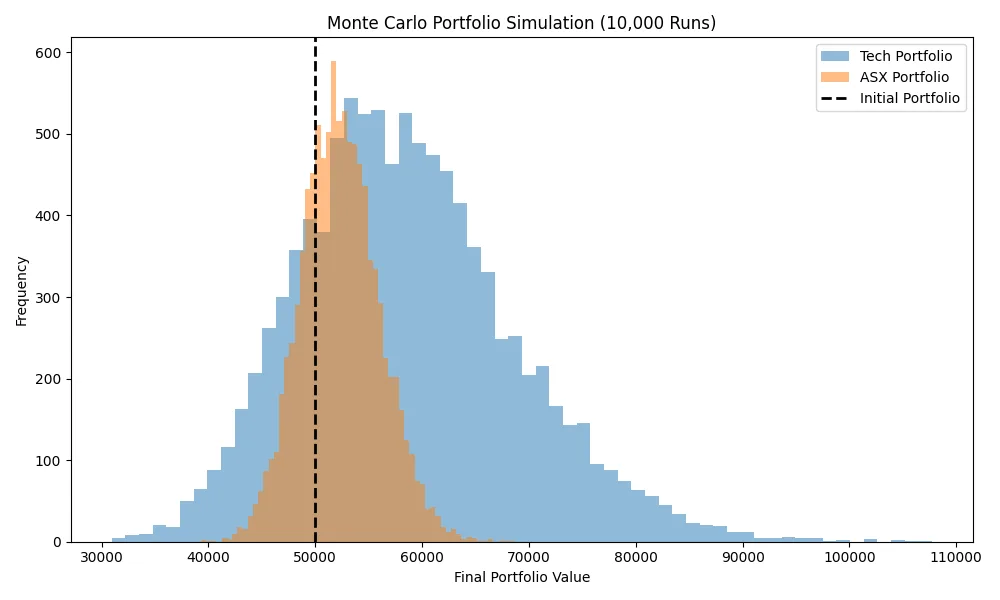
Overlaid histograms of final portfolio value for a tech portfolio and an ASX portfolio over 10,000 Monte Carlo runs.

Portfolio tail risk

10,000 simulated paths compare a correlated tech basket with a diversified ASX basket. The tech basket carried nearly twice the 95% CVaR: $9,603 against $4,817.

Python, pandas, yfinanceRepo
Route
resilience

Route Resilience

Led team StellarBlitz at ISRO's Bharatiya Antariksh Hackathon 2026. Roads extracted from satellite imagery become a graph, ranked by centrality and stress-tested with blockage simulations.

Python, graph theoryRepo
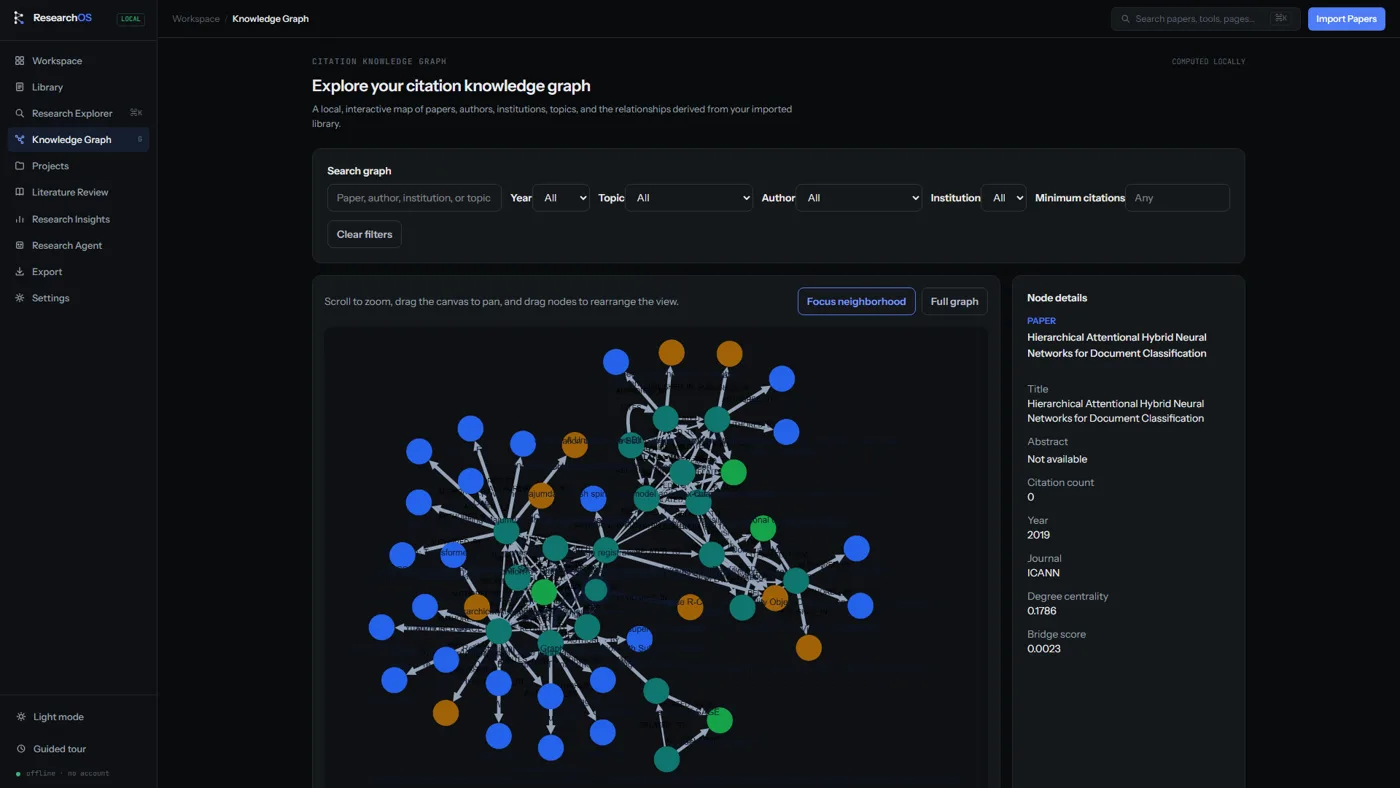
ResearchOS knowledge graph view showing papers as connected nodes with a details panel.

ResearchOS Core

An offline-first research workspace: paper library, PDF reader with page-linked highlights, a citation knowledge graph and literature-review synthesis.

Next.js, TypeScript, PrismaRepo

Talks and roles

Reading a defect's hidden structure from transistor noise

One Slide Presentation track, Student Research Symposium 2026, organised by IEEE MP Section chapters at IIT Indore.

October 2026

Quantum Monte Carlo: faster financial risk estimation?

Poster at KAGADA 2026, IEEE UVCE's national student conference, on quantum amplitude estimation for risk and why theoretical speedups are hard to realise.

October 2026

Finance Lead, NIE Quantum Research Lab

From November 2026

Innovation Policy Consortium finalist

Led a four-person team from Onyx E-Cell to the final round at E-Cell, MIT Manipal.

Samsung Innovation Campus 2026

Selected participant

Learning beyond the syllabus

Probability and Stochastics for FinanceNPTEL, IIT Kanpur. Elite certificate.
Financial Engineering and Risk ManagementColumbia University, Coursera.
Introduction to Dynamical Models in BiologyNPTEL, IIT Guwahati. 85%.
Crash Course on PythonGoogle, Coursera.

Let's talk.

Open to research collaborations, internships and conversations about stochastic modelling, devices or quant finance.